U.S. NFIB Small Business Optimism Little Changed in October
Summary
- NFIB Small Business Optimism Idx down 0.1 pts. to 97.8 in Oct., slightly below its 53-year avg. of 98.0.
- Uncertainty Idx down 6 pts. to 84, lowest level since Dec. ’25.
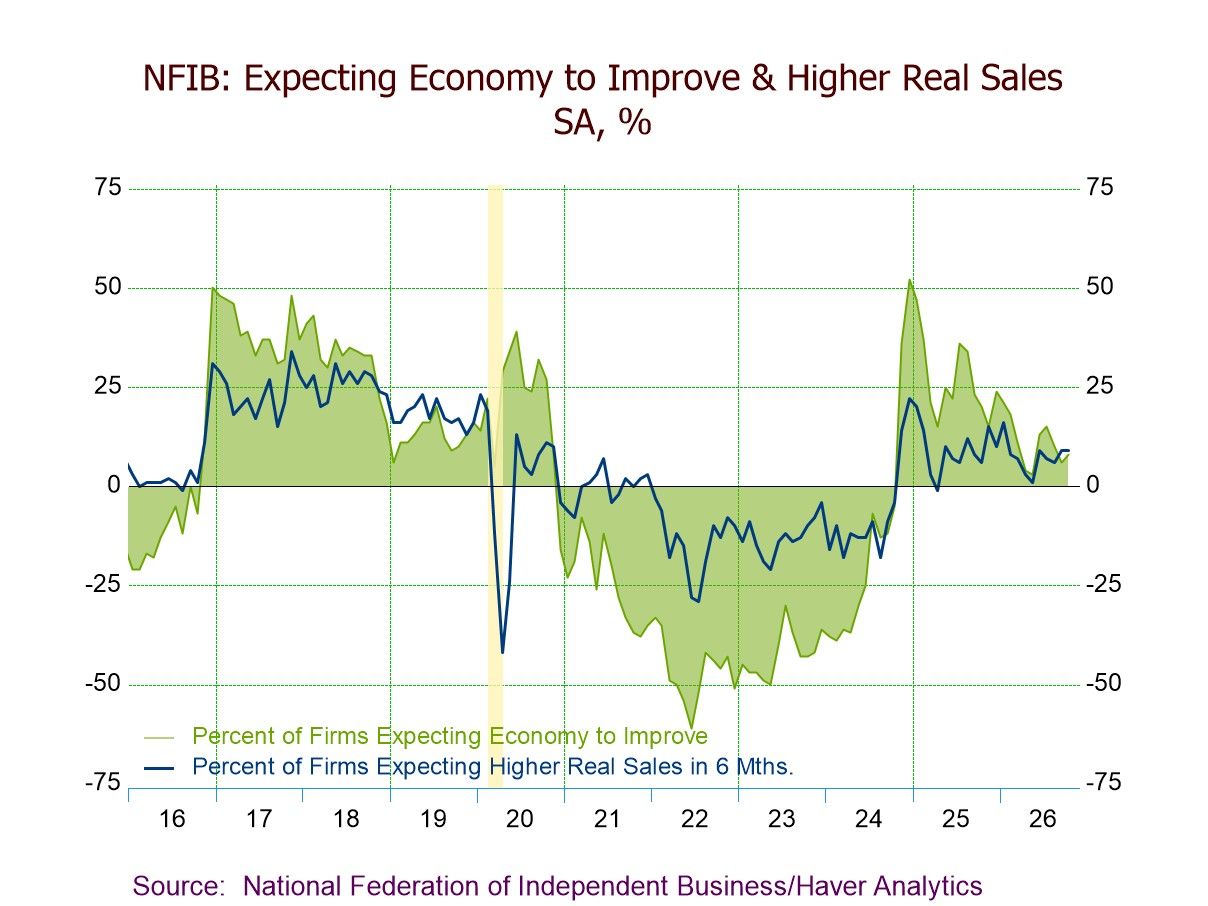
- Expectations for economy up 2 pts. to 8%, positive for the 24th straight month.
- Expected real sales unchanged at 9%, matching highest level since June.
- Plans to expand business up to 11% from September’s 7% (lowest since May).
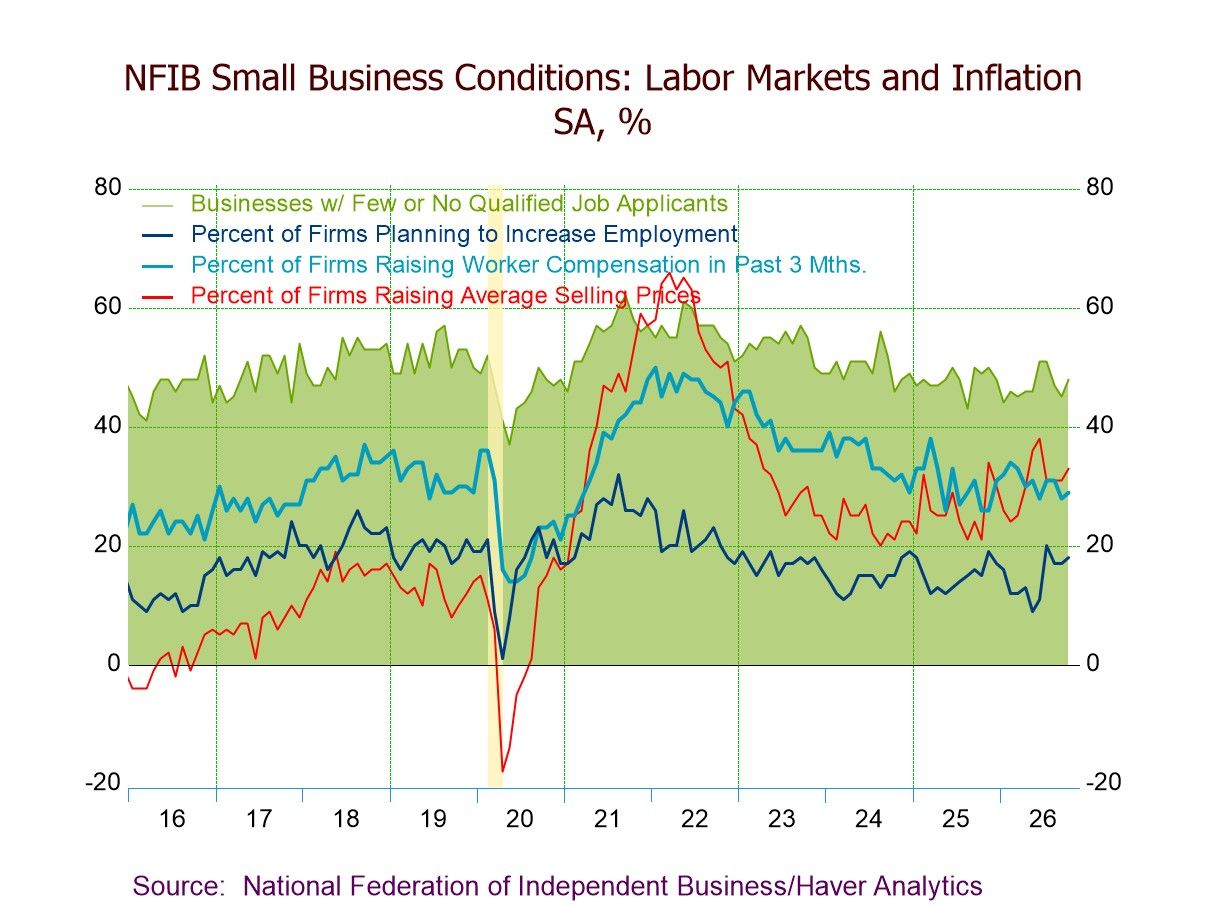
- Hiring plans up to 18%, highest since July; earnings trends down to -23%, lowest since March.
- Avg. selling prices up to 33%, highest since June; planned price hikes up to 37%, highest since July ’22.
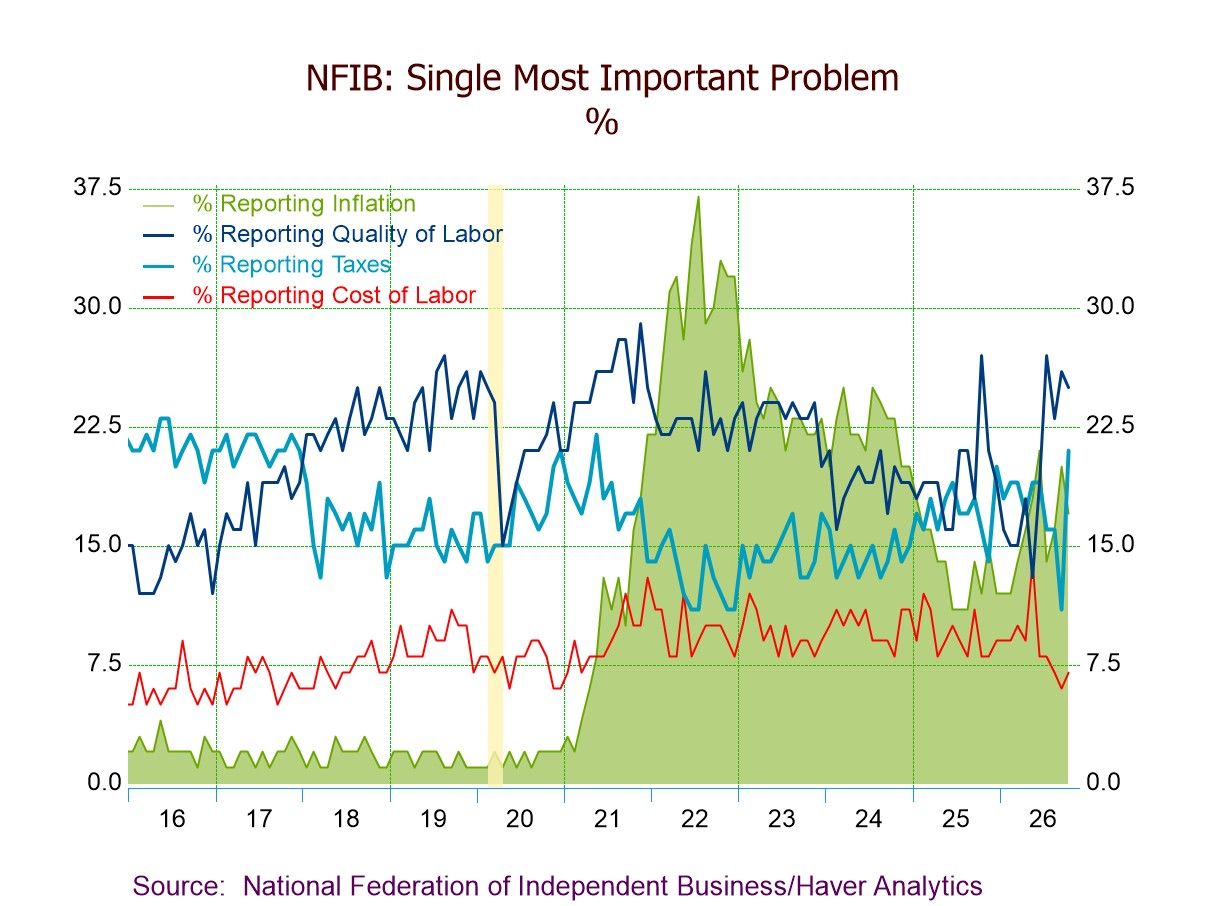
- Top three business concerns: labor quality (25%), taxes (21%), and inflation (17%).
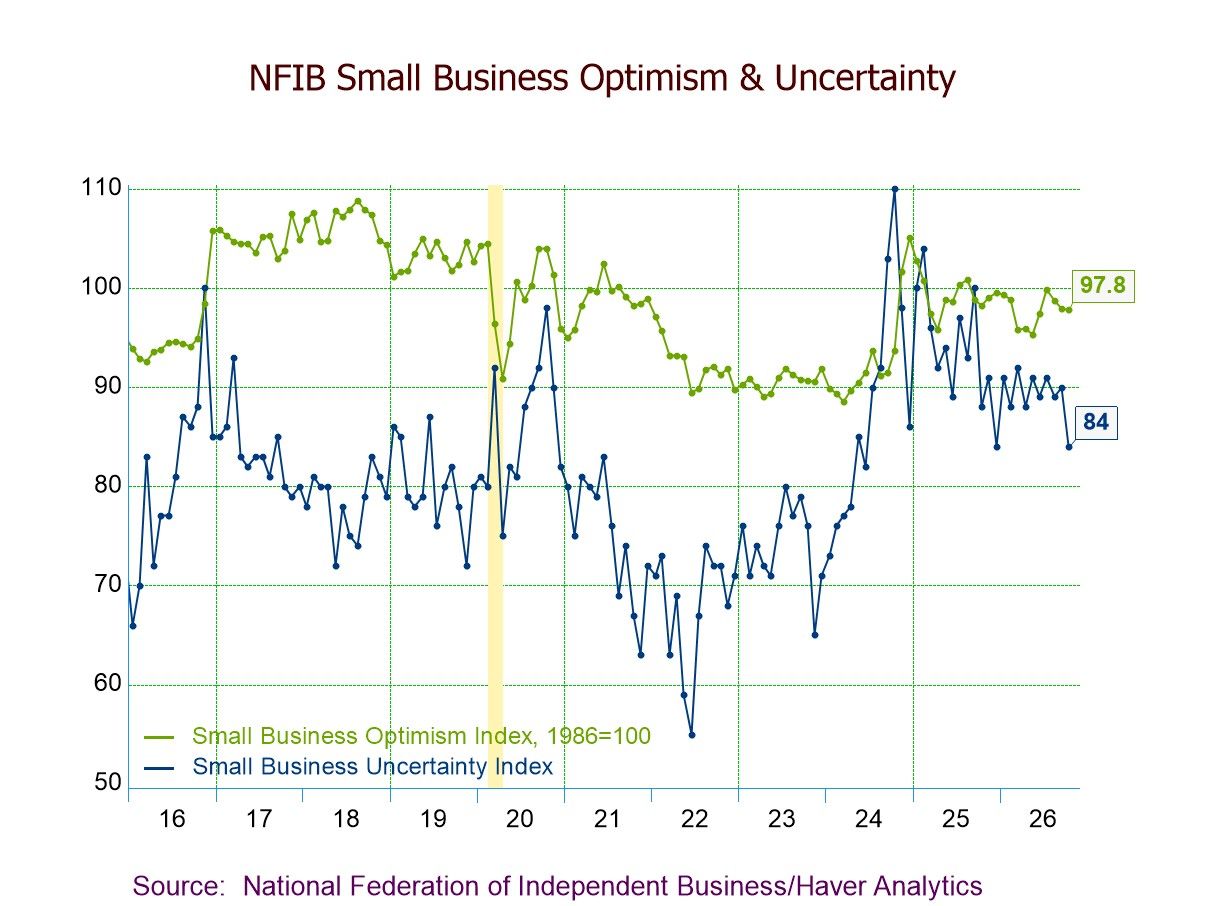
The NFIB Small Business Optimism Index slipped to 97.8 in October from 97.9 in September and 98.7 in August, according to the Small Business Economic Trends survey from the National Federation of Independent Business, indicating that small business sentiment was little changed and declined m/m for the third consecutive month. Job openings and reports that it is a good time to expand increased, while inventory components and earnings trends fell. The index was below its 53-year average of 98.0 for the second consecutive month; it was also below 98.2 in October 2025 and a peak of 105.1 in December 2024, albeit above a low of 88.5 in March 2024. Four of the 10 index components rose, five declined, and one was unchanged. The NFIB Small Business Uncertainty Index fell to 84 in October, matching the lowest level since December 2025, following a one-point rise to 90 in September, while remaining above its historical average of 68. The index was well above a low of 65 in November 2023 but below its record high of 110 in October 2024.
The outlook for business conditions in the next six months, up in the October survey, stayed positive for the 24th straight month. The net balance of respondents expecting the economy to improve rebounded to 8% in October following a four-point decline to 6% in September; these readings were far below a high of 52% in December 2024 but significantly above a record low of -61% in June 2022. Expected real sales held steady at a net 9% in October, matching the highest level since June; the latest result was below a high of 22% in December 2024 but above a low of -18% in August 2024. A net -4% of respondents reported higher nominal sales in the past three months, up from -8% in September and equaling the highest reading since July; the measure remained above a low of -20% in October 2024 but below the recent positive reading of 1% in February and a peak of 9% in June 2021.
Plans to expand the business advanced to 11% in October following a five-point drop to 7% in September (the lowest level since May); the latest figure was below a high of 20% in December 2024 but above a low of 2% in March 2023. Plans to make capital outlays edged down to 21% in October, the lowest level since June, from 22% in September; these numbers were above a low of 16% in May but below a high of 28% in November 2024 and a peak of 31% in October 2021. Expected credit conditions decreased to -5% in October, the lowest reading since June, from -3% in September; this result remained above a low of -11% in November 2023. Meanwhile, a net -3% of respondents viewed current inventory stocks as “too low” in October, down from 0% in September and marking the weakest reading since May; the series had been negative since June 2025, with zero readings only for three months (September 2026, June 2026, and August 2025); a positive reading of 1% was recorded in May 2025.
On the labor front, 48% of respondents reported that qualified workers to fill job openings were hard to find in October, up from 45% in September and posting a three-month high. These numbers were above a low of 43% in August 2025 but below a high of 56% in August 2024 and a peak of 62% in September 2021. A net 18% planned to increase employment in October, up from 17% in September and marking the highest level since July; it remained above a low of 9% in May but below a peak of 32% in August 2021. Notably, 36% reported positions not able to be filled in October, up from 32% in September and matching the highest reading since July; these figures remained above a low of 29% in May but below a high of 51% in May 2022.
Overall earnings trends had remained in negative territory since December 2019. The measure fell to -23% in October, the weakest reading since March, following a one-point decline to -20% in September. These readings were below a recent high of -14% in February and a high of -5% in June 2021 but above a low of -37% in August 2024.
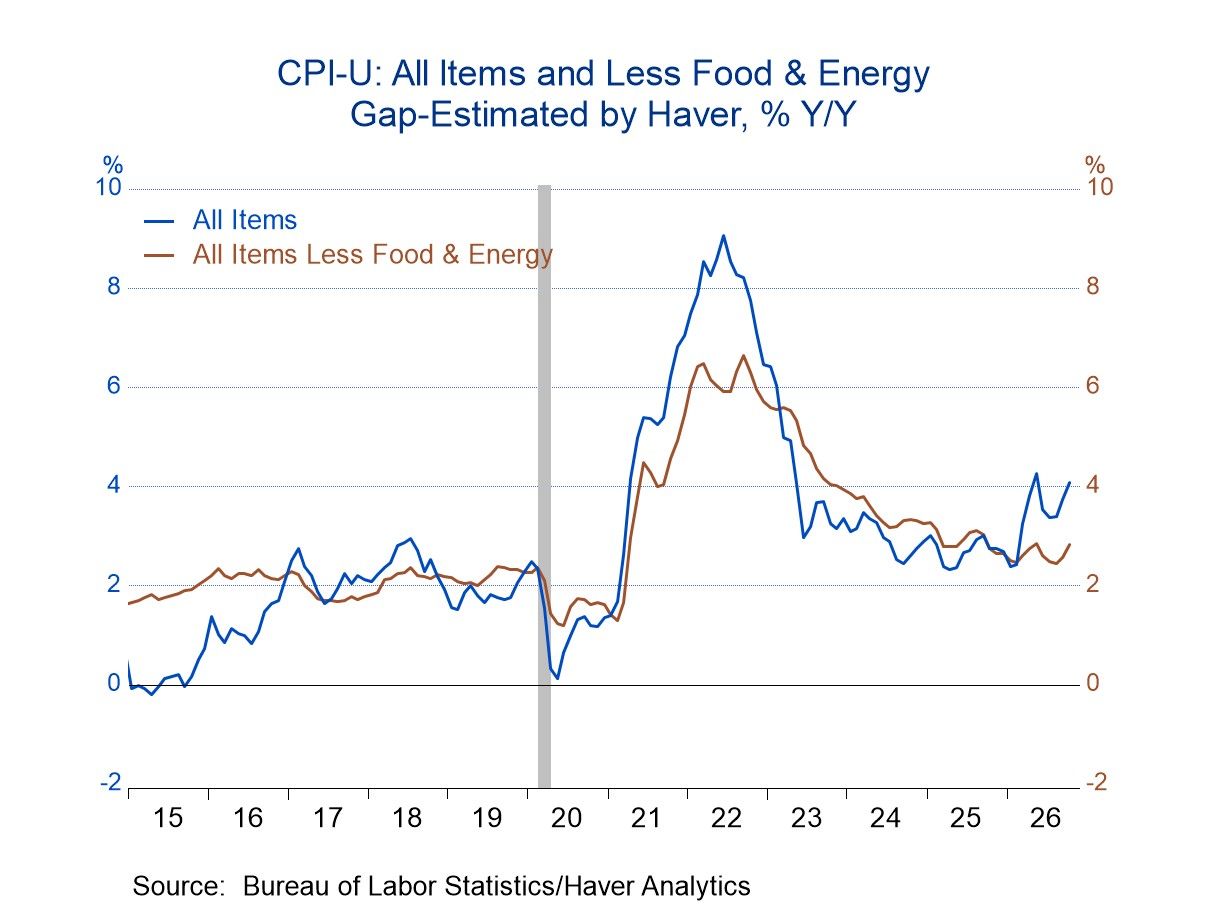
On the pricing front, actual and expected selling prices remained at an elevated level, indicating continued inflationary pressures. The net percent of firms raising their average selling prices increased to 33% in October, the highest level since June, after holding at 31% for three successive months. The latest reading was up from a low of 20% in August 2024 but well below a peak of 66% in March 2022. The percentage planning to raise prices jumped to 37% in October, the highest reading since July 2022, following a three-point rise to 31% in September; these readings remained above a low of 21% in April 2023.
Wage inflation remained relatively high in the October survey. A net 29% of respondents raised compensation during the last three months, up from 28% in September. It was above a low of 26% in November 2025 but below a high of 46% in February 2023 and a peak of 50% in January 2022. A net 24% of firms planned to raise worker compensation in the next three months, up from 20% in September and equaling the highest level since December 2025; this was above a low of 17% in June but below its highs of 28% in November 2024, 30% in November 2023, and 32% in October 2022.
Labor quality was cited as the single most important problem facing small businesses for the fourth straight month, as reported by 25% of NFIB members in October, down from 26% in September. Taxes ranked second as the next most important problem, as reported by 21% of respondents in October, surging from 11% in September and representing the highest since May 2021. Inflation ranked third and remained a key challenge for small businesses, as reported by 17% of respondents in October, down from a three-month high of 20% in September; these readings were well below a peak of 37% in July 2022. Other concerns (in October vs. September) included government requirements (7% vs. 7%), labor costs (7% vs. 6%), insurance cost/availability (7% vs. 6%), poor sales (6% vs. 11%), and competition from large businesses (5% vs. 6%).
According to the Small Business Administration, there are 33 million small businesses in the United States, which employ 62 million workers. The NFIB surveys anywhere from 500 to 2000 respondents each month and the typical firm employs 10 people and reports gross sales of about $500,000 a year. The NFIB figures can be found in Haver’s SURVEYS database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Asia