- Headline +0.6% m/m, first monthly gain in three mths.; +1.6% y/y, fourth straight y/y rise.
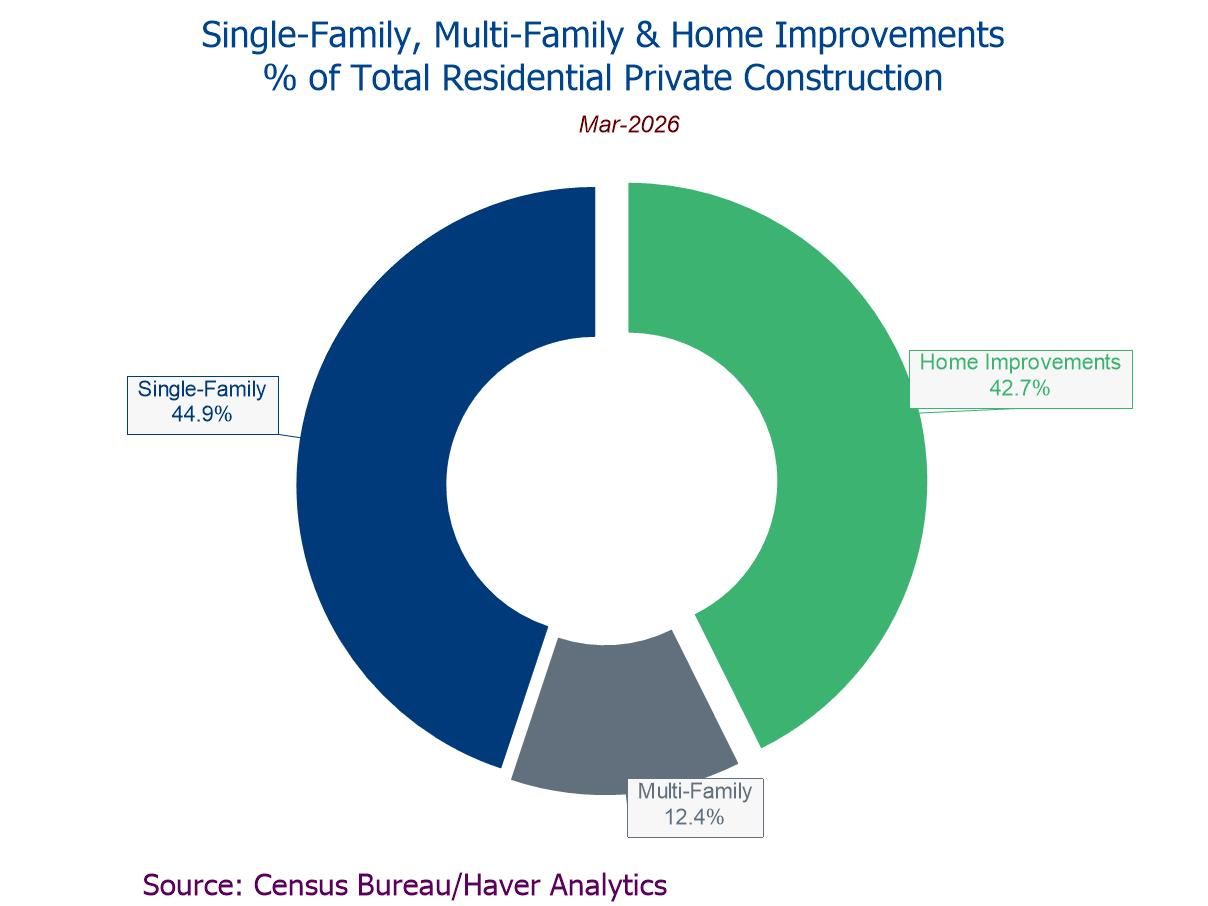
- Residential private construction +1.7% m/m, driven by a 2.7% rebound in single-family building.
- Nonresidential private construction -0.2% m/m, fifth decline in six mths.
- Public construction -0.2% m/m, led by a 2.3% drop in residential public building.
Introducing
Winnie Tapasanun
in:Our Authors
Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.

Publications by Winnie Tapasanun
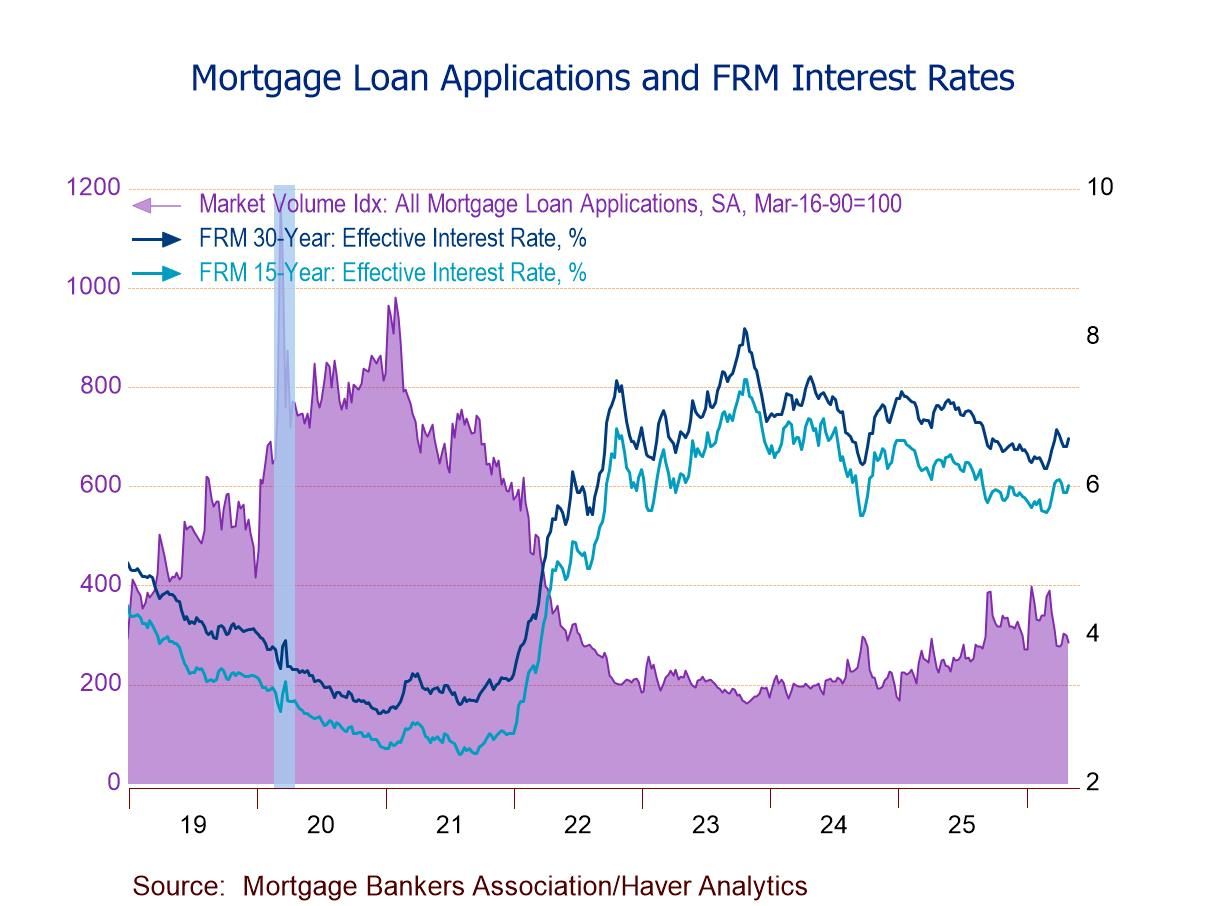
- Purchase applications -3.7% w/w, first decrease in three weeks; refinancing loan applications -5.0% w/w, second consecutive drop.
- Effective interest rate on 30-year fixed loans up 10bps to 6.64%, a four-week high.
- Average loan size up for the fifth straight week, highest level since the March 6 week.
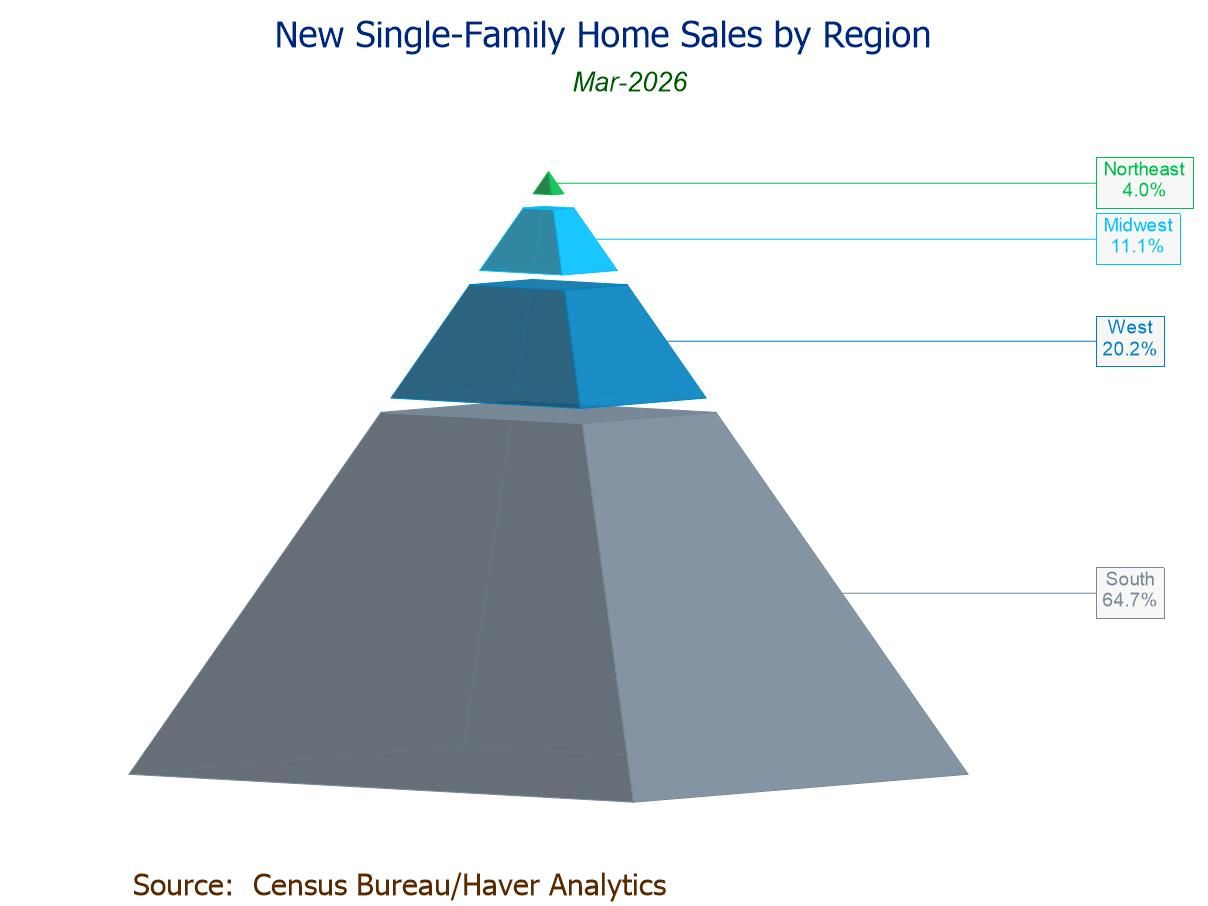
- Sales +7.4% m/m (+3.3% y/y) to 682,000 in Mar., a 3-month high; +8.9% m/m (-1.1% y/y) to 635,000 in Feb.
- Sales m/m up in the Northeast and South, down in the Midwest and West; sales y/y up in all regions except the West (-12.7% y/y).
- Median sales price -5.3% m/m to $387,400, lowest since Jul. ’21; avg. price -3.4% m/m to $503,100, lowest since Jul. ’25.
- Months' supply: 8.5 mths. in Mar., a 3-month low; 9.1 mths. in Feb.
 USA| May 04 2026
U.S. Factory Orders Exceed Expectations in March
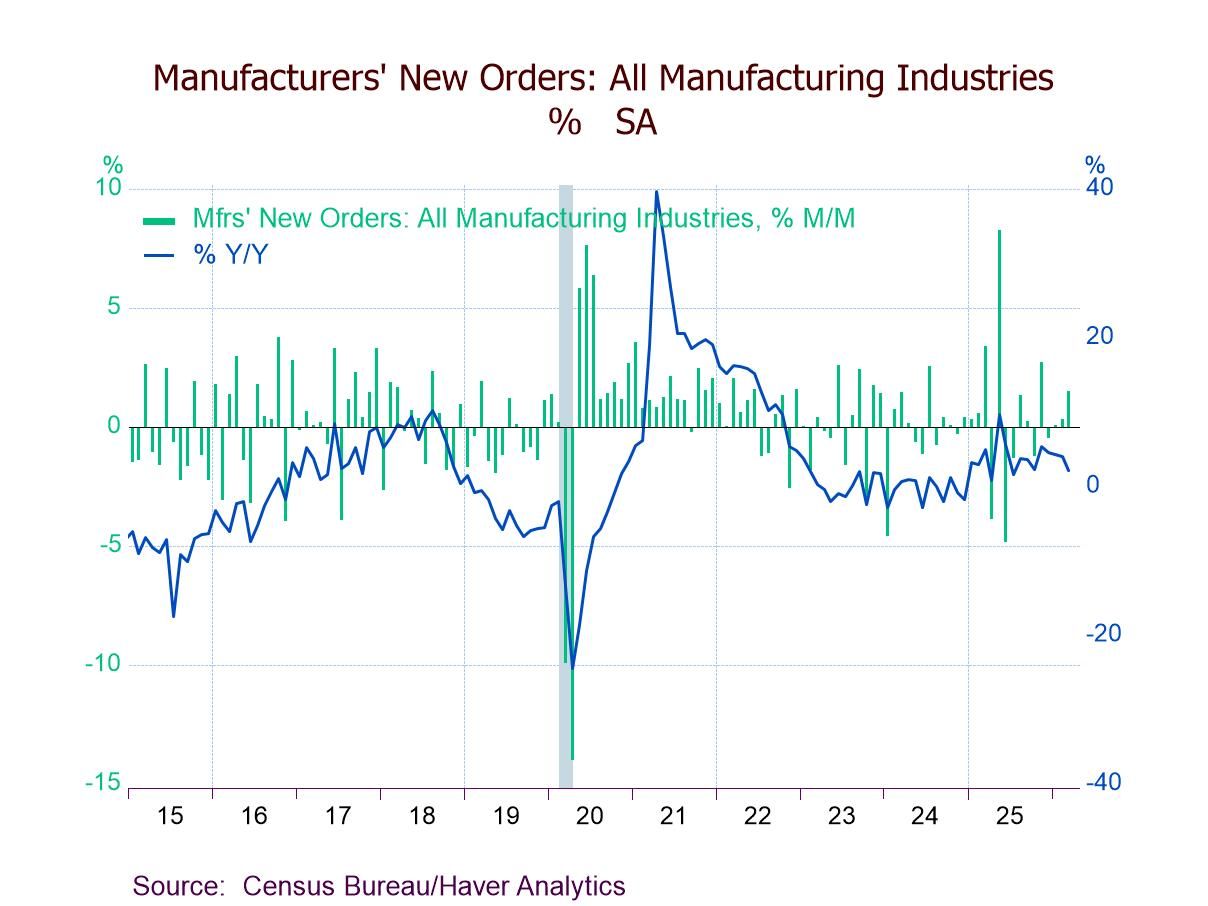
- Factory orders +1.5% m/m (+2.1% y/y) in Mar.; 9.5% above the Jan. ’24 low.
- Durable goods orders +0.8%, first m/m increase since Nov.; nondurable goods orders +2.1%, largest of four straight m/m gains; shipments +1.4%, fourth successive m/m rise.
- Transportation orders +0.8%, driven by m/m surges of 30.9% in ships & boats and 17.8% in defense aircraft orders.
- Computers & electronic products +3.6%, fastest of seven consecutive m/m rises.
- Unfilled orders +0.1%, eighth straight m/m increase.
- Inventories +0.6%, biggest of five consecutive m/m gains.
 USA| May 01 2026
U.S. ISM Manufacturing PMI Steady in April; New Orders and Production Growing; Employment Contracting
- ISM Mfg. PMI at 52.7 in Apr. and Mar.; fourth consecutive month of expansion.
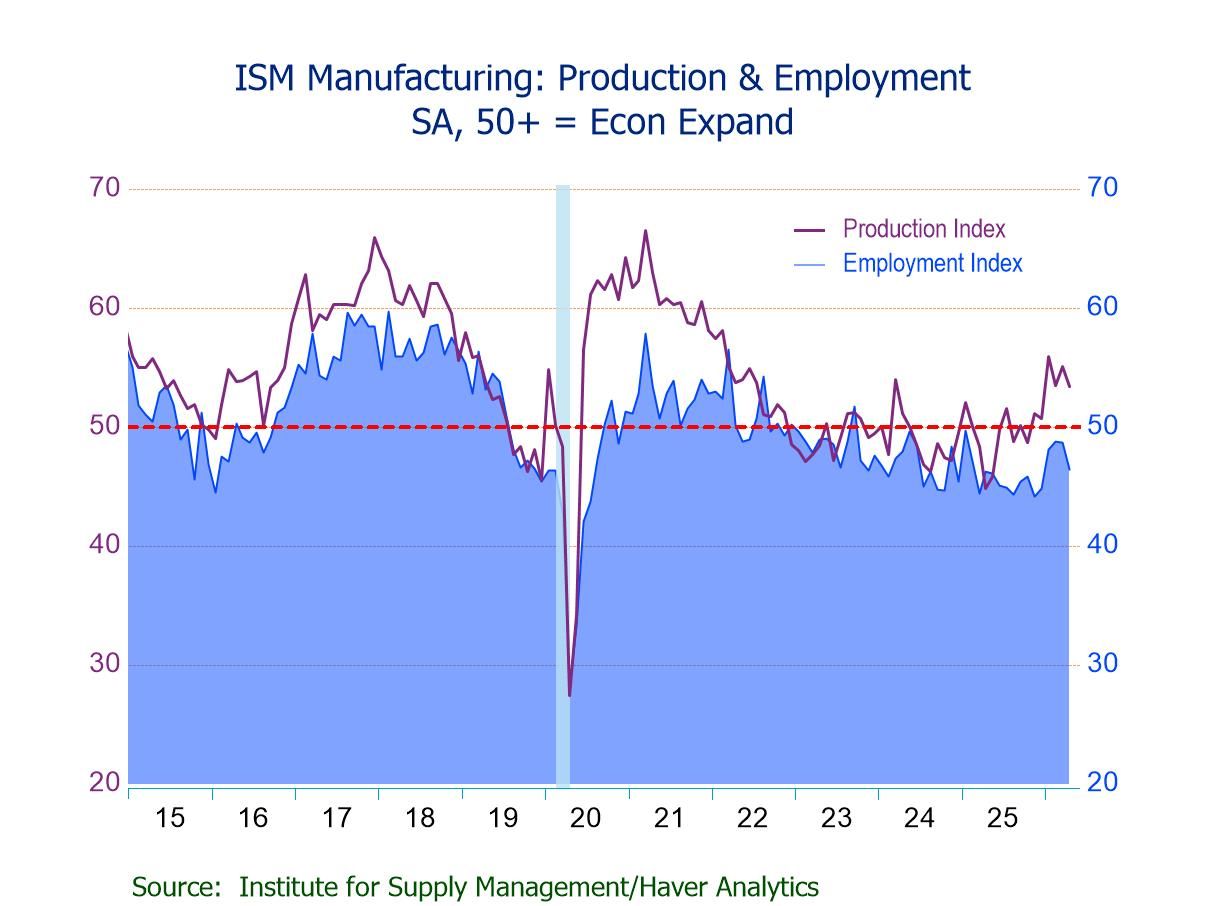
- Production (53.4) expands for the sixth straight mth.; new orders (54.1) for the fourth successive mth.
- Employment (46.4) contracts for the 31st straight mth.; at a four-month low.
- Prices Index (84.6) highest since Apr. ’22; prices rising for the 19th consecutive mth.
- Exports (47.9) contract; imports (50.3) still grow but at a three-month low.
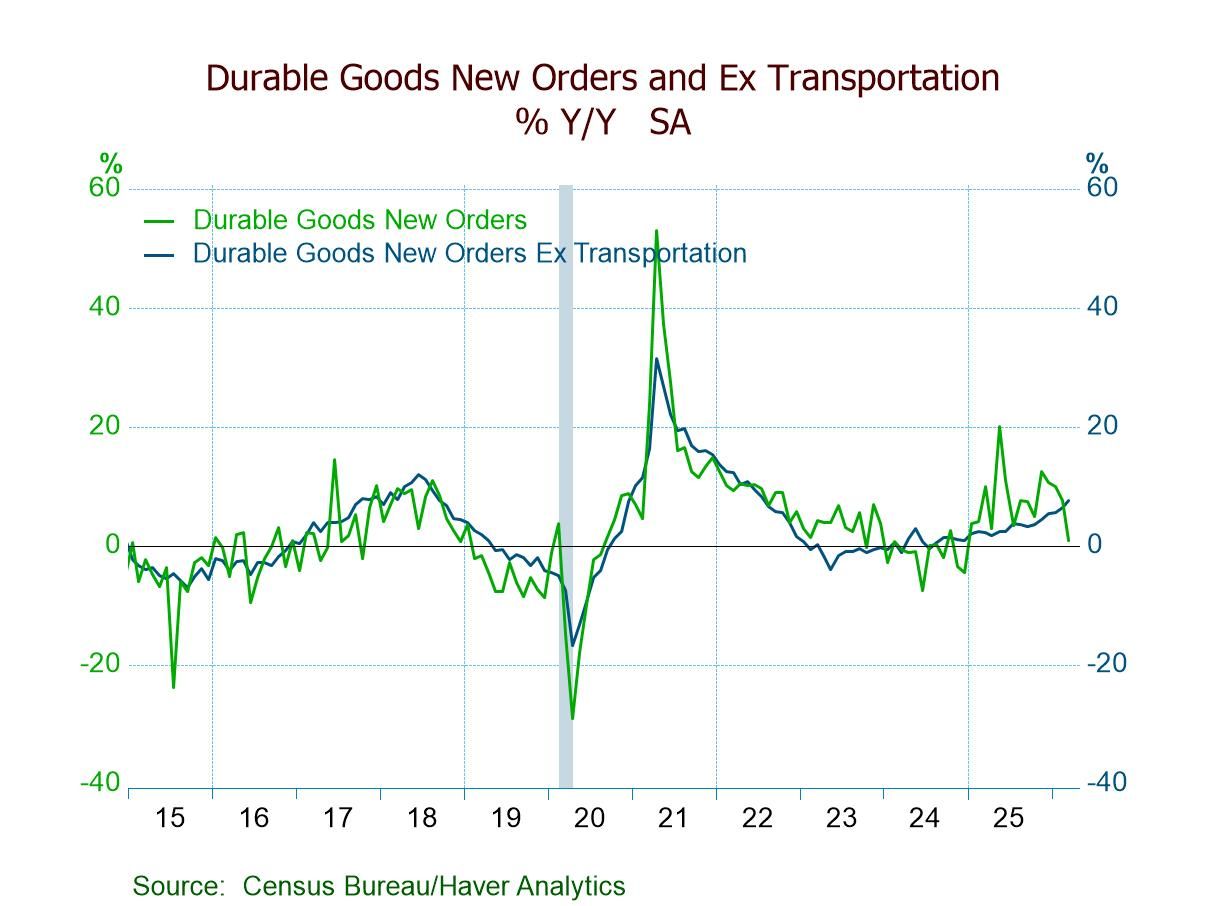
- March headline orders +0.8% m/m, first increase in four mths.; +0.8% y/y, lowest since Dec. ’24.
- Defense aircraft & parts +16.9% m/m following February’s +0.5%.
- Transportation orders +0.8%, first m/m rise since Nov.; orders ex transp. +0.9%, 11th straight m/m increase.
- Core capital goods shipments +1.2%, sixth m/m gain in seven mths., pointing to a solid contribution to Q1’26 GDP from business equipt. spending.
- Durable goods shipments +0.7%; unfilled orders +0.1%; inventories +0.2%.
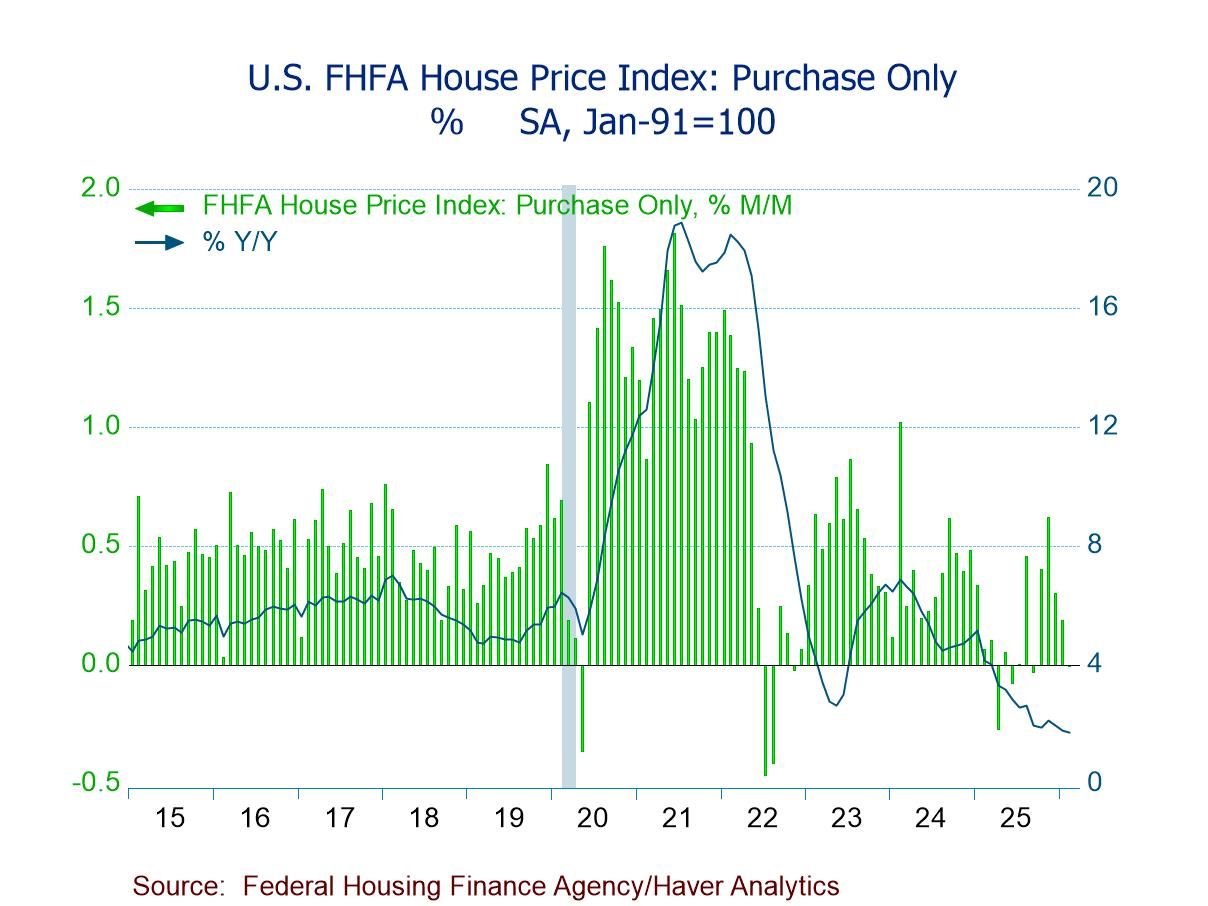
- February FHFA HPI 0.0% m/m; +1.7% y/y, lowest since Mar. ’12.
- House prices down m/m in four of nine census divisions, led by Mountain (-1.1%); up in four, driven by South Atlantic (+0.6%); flat in East North Central.
- House prices up y/y in six of nine regions, led by Middle Atlantic (+4.2%), but down in Mountain (-0.7%), Pacific (-0.4%), and West South Central (-0.1%).
 USA| Apr 22 2026
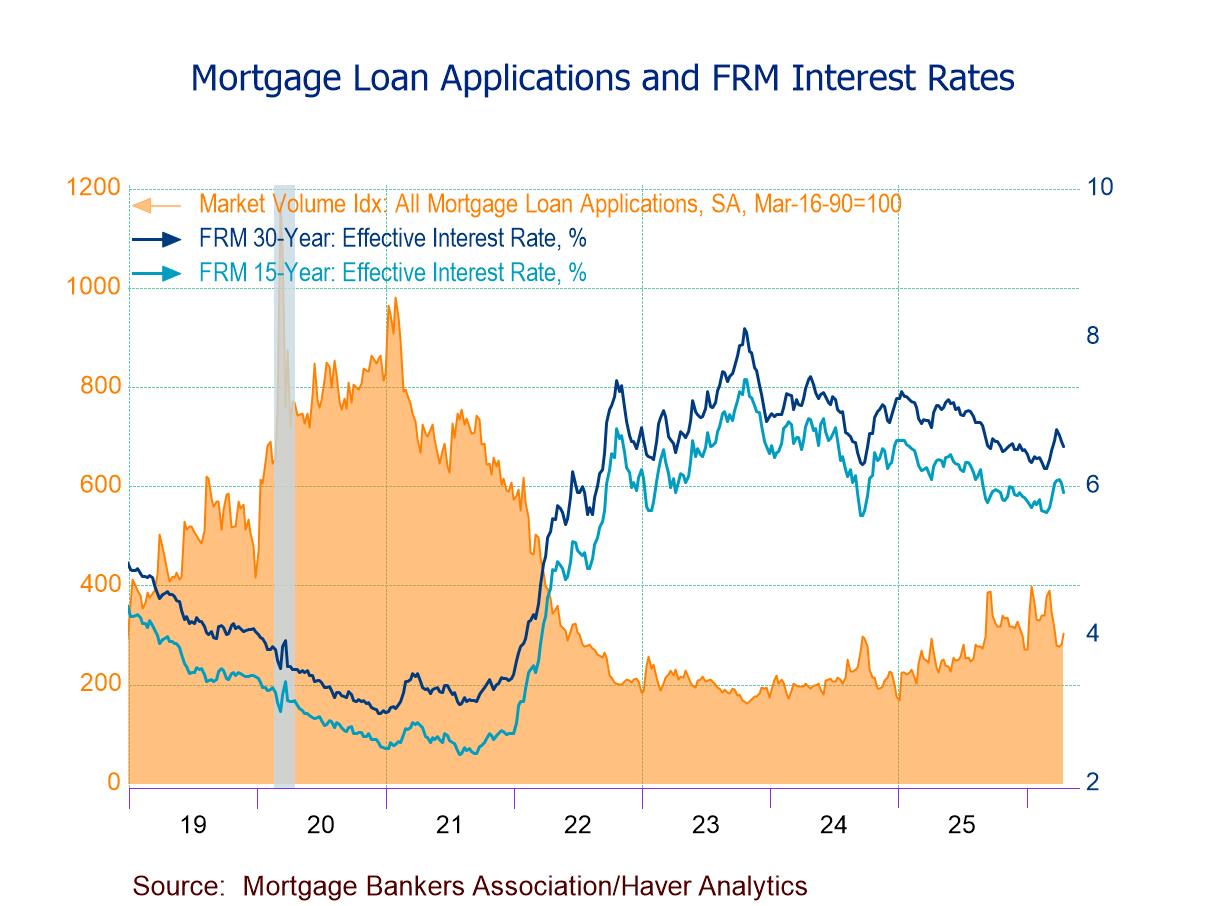
U.S. Mortgage Applications Up 7.9% in the April 17 Week, Largest Gain Since Late February
- Purchase applications +10.1% w/w, biggest increase since the Jan. 9 week; refinancing loan applications +5.8% w/w, second consecutive rise.
- Effective interest rate on 30-year fixed loans down 7bps to 6.53%, a five-week low.
- Average loan size up for the third straight week, highest level since the March 13 week.
 USA| Apr 21 2026
U.S. Pending Home Sales Up for Second Consecutive Month in March
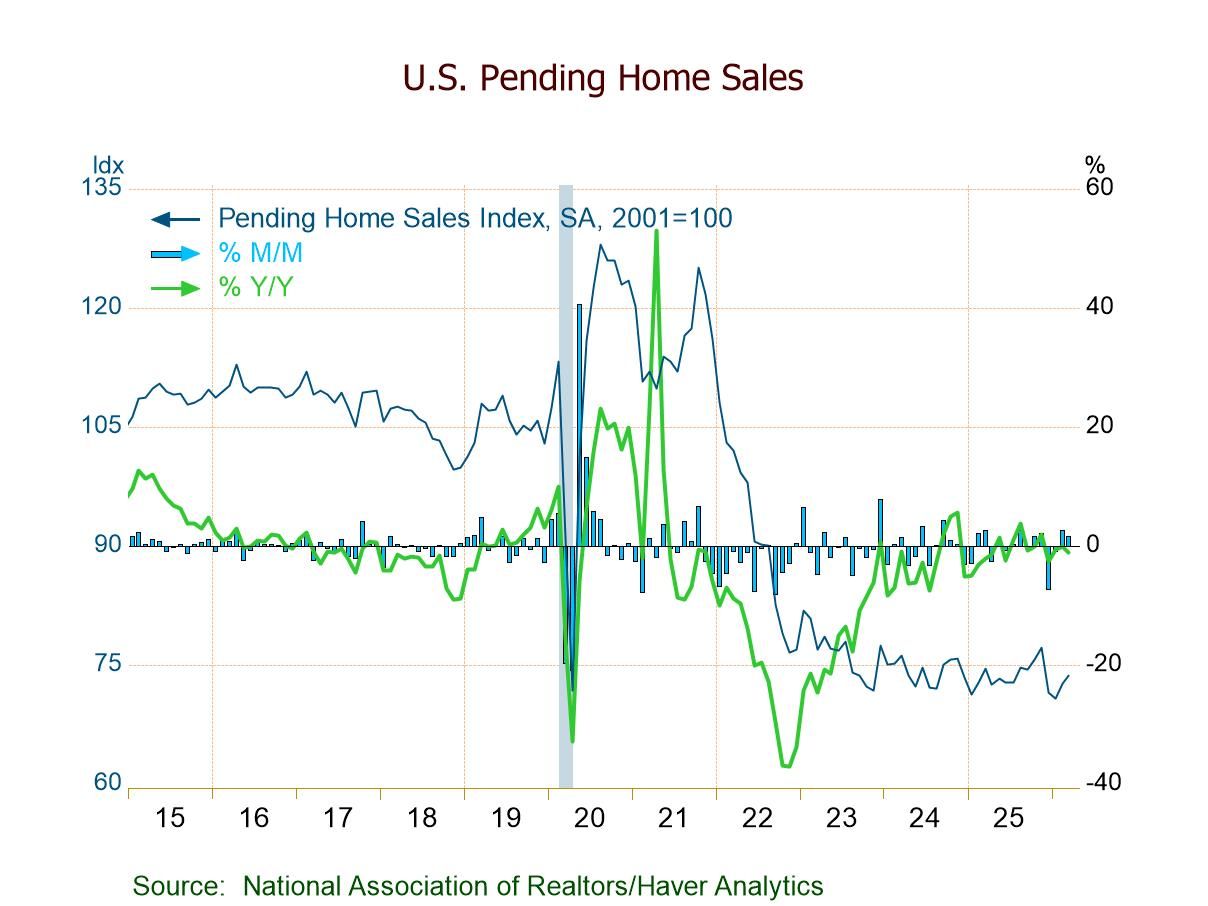
- PHSI +1.5% m/m (-1.1% y/y) to 73.7 in Mar., highest level since Nov.
- Home sales m/m up in the Northeast (+4.4%) and South (+3.9%); down in the Midwest (-1.3%) and West (-2.6%).
- Home sales y/y down in the Northeast (-6.5%), Midwest (-3.1%), and West (-1.7%); up in the South (+2.3%).
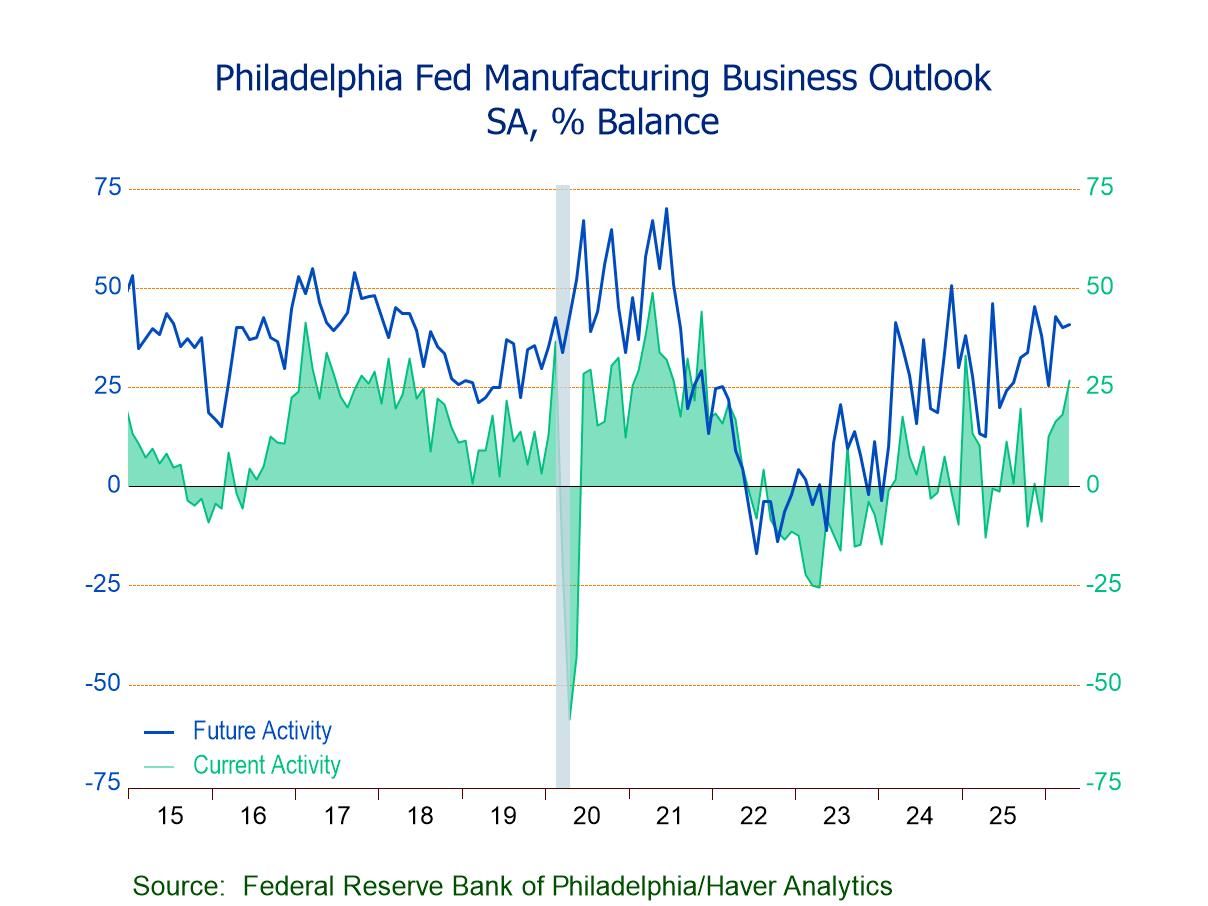
- Current General Activity Index up 8.6 pts. to 26.7 in Apr.; fourth consecutive m/m rise.
- Positive: Shipments (34.0), highest since May ’22; New Orders (33.0), highest since Nov. ’21.
- Negative: Employment (-5.1), lowest since June ’25; Unfilled Orders (-10.2), ninth straight contraction.
- Inflation indicators at eight-month highs and well above long-run nonrecession avgs.
- Future General Activity Index up to 40.8; most subindexes down but still positive; future price indexes still above long-run avgs.
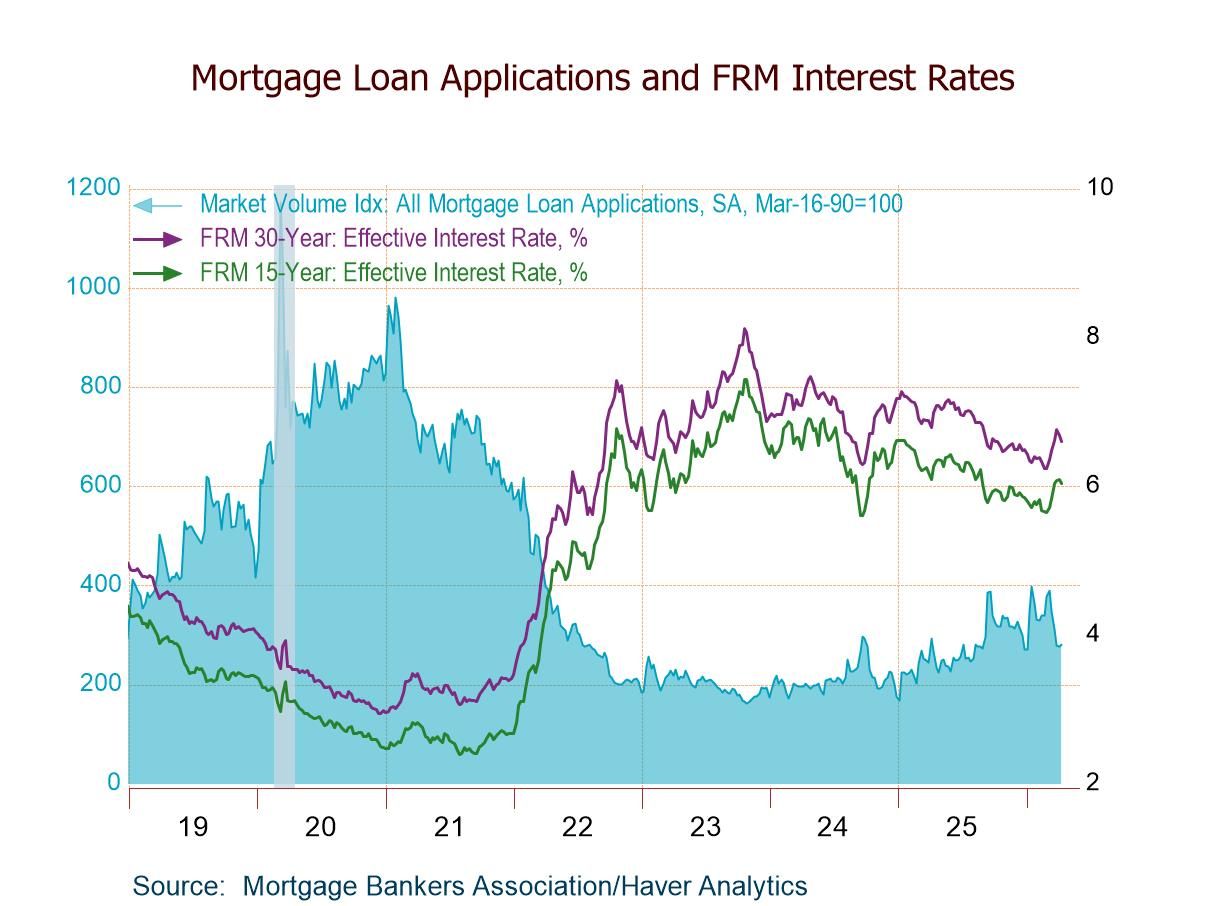
- Purchase applications -1.0% w/w, third decline in four weeks; refinancing loan applications +5.1% w/w, first rise since the March 6 week.
- Effective interest rate on 30-year fixed loans down 8bps to 6.60%, a four-week low.
- Average loan size up to the highest level since the March 13 week.
 USA| Apr 13 2026
U.S. Existing Home Sales Drop in March to a Nine-Month Low
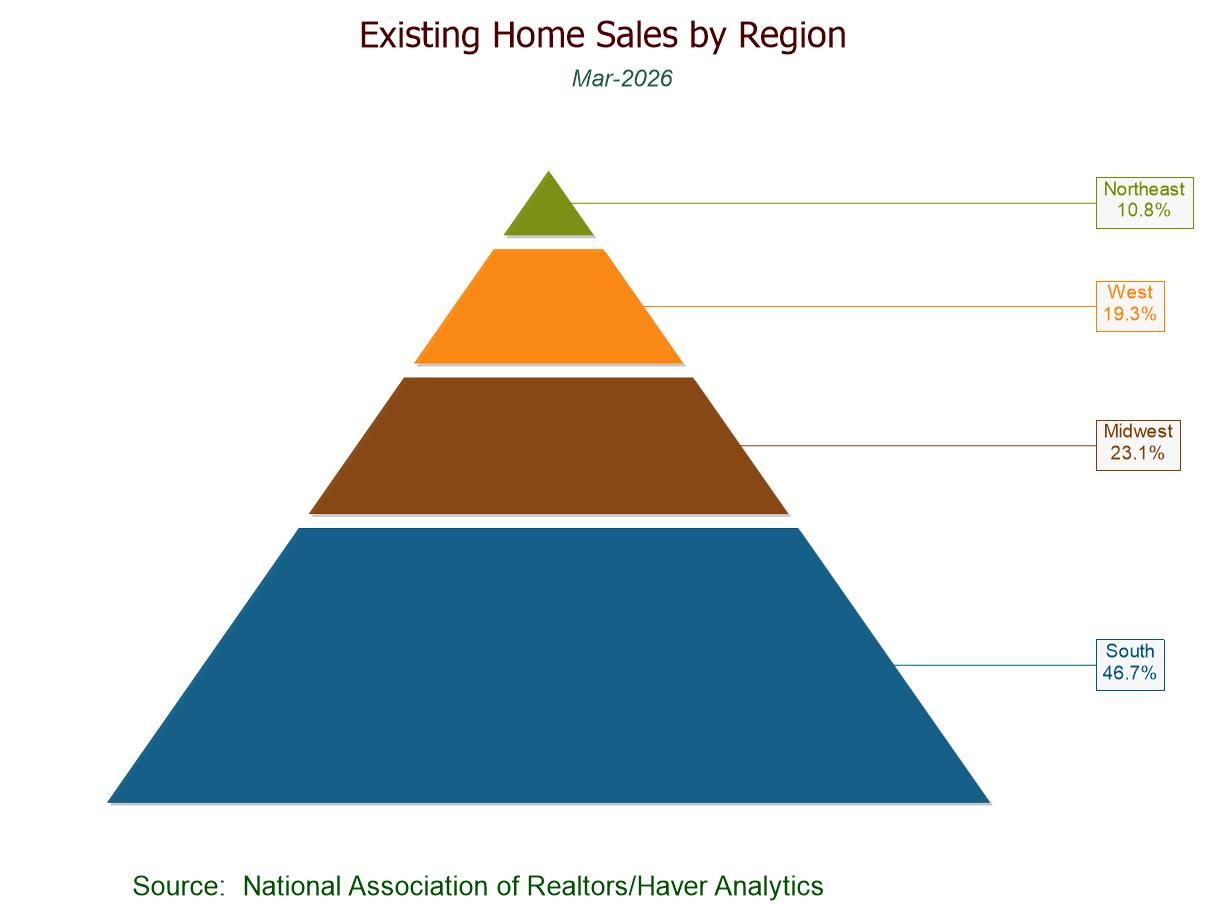
- March sales -3.6% m/m to lower-than-expected 3.98 mil.; -1.0% y/y, fifth straight y/y decrease.
- Broad-based regional m/m declines: Northeast (-8.5%), Midwest (-4.2%), South (-3.1%), West (-1.3%); y/y sales up in the South and West but down in the Northeast and Midwest.
- Median sales price +2.7% (+1.4% y/y) to $408,800, highest since November.
- Unsold inventory +3.0% (+2.3% y/y) to four-month-high 1.36 mil. units; 4.1 months' supply.
- of15Go to 5 page